Learn
Why Roofing Contractors File Supplements (and What It Means for Your Business)
Written for contractors: the adjuster's first estimate is a starting point, not a final number. Here's the business case for a real supplement system — and how to build one that gets approved.
The Math Nobody Talks About
Here's a number worth sitting with: on a typical residential roof claim, the gap between the adjuster's first estimate and the legitimate completed scope routinely runs into the thousands of dollars. Not because adjusters are dishonest — because a one-hour inspection from a ladder cannot see what tear-off reveals, and because the first estimate is written fast, from templates, under volume pressure.
Every dollar of that gap that you don't recover is a dollar your company absorbs: in thinner margins, in callbacks you can't bill for, in work done right that the paperwork says was done cheap. Contractors who treat supplements as an afterthought — something the office "gets around to" — are systematically leaving legitimate revenue uncollected on job after job. Contractors who treat supplements as a system collect it.
If you're new to the mechanics — what a supplement is, how it differs from a reinspection, what the process looks like — start with our plain-English guide to what a roofing supplement is and when you need one. This article is about the business side: why it matters to your bottom line and how to build the system.
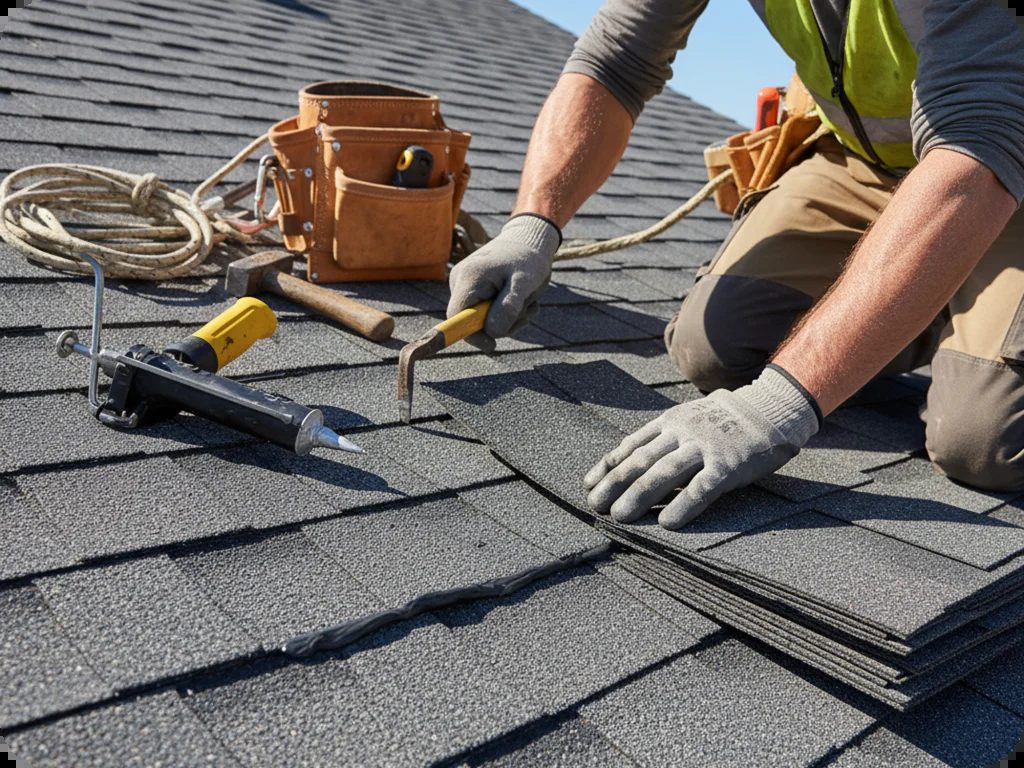
Why First Estimates Come Up Short
Understanding why estimates miss things helps you document the right things. The causes are structural, not personal:
- Limited inspection time. A field adjuster may spend 30–60 minutes on the property, often without walking every slope. Things that require close inspection — deteriorated step flashing, soft decking, hail bruising on a shaded slope — get missed.
- Hidden conditions. Nobody knows the decking condition until the shingles come off. The first estimate includes a token decking allowance (or none); the real quantity appears at tear-off. This is the single most common mid-job supplement.
- Template scoping. Estimates are built from price-list line items applied quickly. Items that require judgment calls — whether flashing can be reset or must be replaced, whether code requires ice and water shield in a particular valley — default to the cheaper option.
- Code and manufacturer requirements the inspector didn't check. Current building code and shingle manufacturer specs require things the original installation may predate. If the policy includes ordinance-or-law coverage, those upgrades belong in the scope — but only if someone documents them.
None of this is an accusation. It's the nature of a high-volume estimating process. Your supplement system exists to complete the picture the first pass couldn't.
The Items That Pay for the System
Across thousands of claims, the same categories show up under-scoped again and again. Learn to spot them on every job and your supplement hit rate climbs immediately:
- Decking replacement quantities. The classic. Photograph every soft or damaged sheet at tear-off, measure in squares, submit with the revised estimate. Carriers expect this supplement — documented properly, it rarely gets real pushback.
- Flashing: replacement vs. detach-and-reset. Estimates routinely write step flashing, counter flashing, and pipe jacks as resets. Old flashing that's lifted during tear-off rarely reseats properly — photograph the condition and write it as replacement.
- Drip edge on rakes and eaves. Frequently missing entirely from the first estimate. Small per-foot cost, large aggregate across a full perimeter.
- Ice and water shield. Code-required in valleys and at eaves in many jurisdictions; often absent from the original scope.
- Ridge vent quantities. Under-measured more often than you'd expect.
- Steep and high charges. Labor multipliers for pitch and stories that the base price list doesn't include. If the estimate was priced as a walkable single-story and the roof is a steep two-story, the labor lines are wrong.
- Code upgrades. Ventilation, underlayment, fastening patterns — cite the specific code section and the policy's ordinance-or-law provision.
Building the System: What Gets Approved
Desk adjusters approve supplements that make their decision easy. Every submission should be a complete package:
- Revised estimate in the carrier's format and price list — showing exactly which lines changed. Never a lump sum.
- Photos proving each added item — dated, with scale, slope by slope. Photo discipline is the highest-ROI habit in supplementing.
- Measurements for every quantity change. Linear feet, squares, counts.
- Code citations for upgrade items — the specific section, not "per code."
- A cover note referencing the claim number and listing changes line by line with their supporting documentation.
Submit complete packages, not drips — five partial submissions create five review cycles. Respond to reviewer questions within a day or two. And document every submission: date, method, claim number, contents. When a supplement goes missing in the carrier's system (it happens), your records turn a reconstruction project into a two-minute resend.
The Reputation Question
Let's address the elephant: some contractors hear "supplement" and think "padding the claim." Carriers track supplement patterns by contractor, and a reputation for inflated or frivolous supplements poisons every future submission — and can draw the kind of attention nobody wants.
The line is bright and simple: supplements document real, legitimate costs the first estimate missed. Photographed, measured, priced from the price list, tied to the policy. That's not padding — it's completing the scope. The contractors with the best supplement approval rates aren't the most aggressive; they're the most thorough. Their submissions read like inspection reports, not arguments.
There's a second reputation effect worth noting: homeowners talk. A contractor who explains the supplement process honestly — "the first estimate missed X, here's the documentation, here's what we're submitting and why" — earns trust that turns into referrals. The supplement conversation, handled well, is a marketing asset.
For contractors: systematize your supplements
The Contractor's Supplement Template Pack ($197) gives you line-item templates for the items adjusters miss most, photo checklists for bulletproof documentation, measurement worksheets, and adjuster-tested submission scripts — the complete system, ready to run on your next claim. One approved supplement typically pays for it many times over.